The Ledger Level 3: Budget & emergency fund
The 50/30/20 budget, tested on our kitchen table
Mom runs the Coins household on one simple rule. Here is the split, the real numbers, and the month it nearly fell apart.
Told by Mom
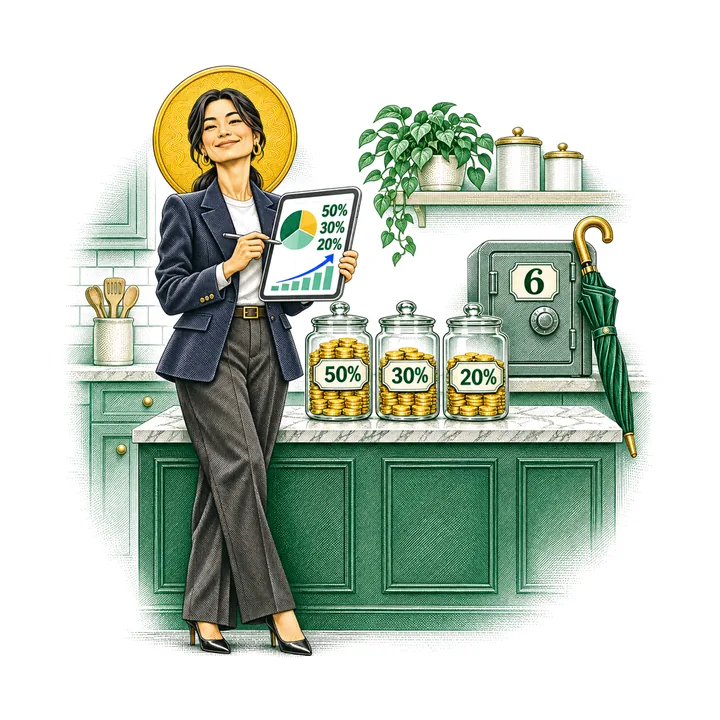
On the first of every month I sit down at the kitchen table with my tablet, a cup of coffee and three jars that are honestly there for Lil. Twenty minutes later every dollar we will earn that month has a job.
The rule I use is called 50/30/20. It is not magic. It is just simple enough that I keep doing it.
The split
Take your take-home pay, the amount that actually lands in your account after taxes. Then:
- 50 % for needs. Rent or mortgage, groceries, utilities, insurance, the minimum payments on any debt.
- 30 % for wants. Restaurants, hobbies, streaming, Dad's gadgets.
- 20 % for the future. Emergency fund first, then extra debt payments, then investing.
Our numbers
Say a family brings home $5,800 a month. The split looks like this:
| Bucket | Share | Per month |
|---|---|---|
| Needs | 50 % | $2,900 |
| Wants | 30 % | $1,740 |
| Future | 20 % | $1,160 |
If your needs are more than half, you are not failing. Rent in a lot of cities makes 50 % impossible. Then the split becomes 60/20/20 for a while, and you work on the biggest need first.
The emergency fund comes first
Before a single dollar of the 20 % goes into investing, we build a cushion of three to six months of needs. With needs at $2,900 that is between $8,700 and $17,400.
It sounds like a lot. At $1,160 a month, the three-month version takes about eight months. We kept it in a separate savings account so it was not sitting next to the grocery money looking tempting.
The month it nearly fell apart
In March the car needed $1,400 of repairs and Dad bought a pizza oven in the same week. The pizza oven came out of his wants money for the next two months. The car came out of the emergency fund, which is exactly what it is for. Then we spent the next month refilling it.
That is the whole point. A budget is not a diet you fail. It is a plan you adjust.
Start this month
- Write down your take-home pay.
- List your needs and add them up.
- Set the wants number and stick to it, even when it hurts a little.
- Move the 20 % on payday, before you can spend it.
If the 20 % feels impossible, start with 5 %. A small habit you keep beats a big one you quit in April.
The Coins is education and entertainment, not financial, tax or investment advice. The family is fictional. Numbers are examples; past returns do not guarantee future results.